
01
Real Property
39
Years
Commercial building structures are generally depreciated over a 39-year recovery period.
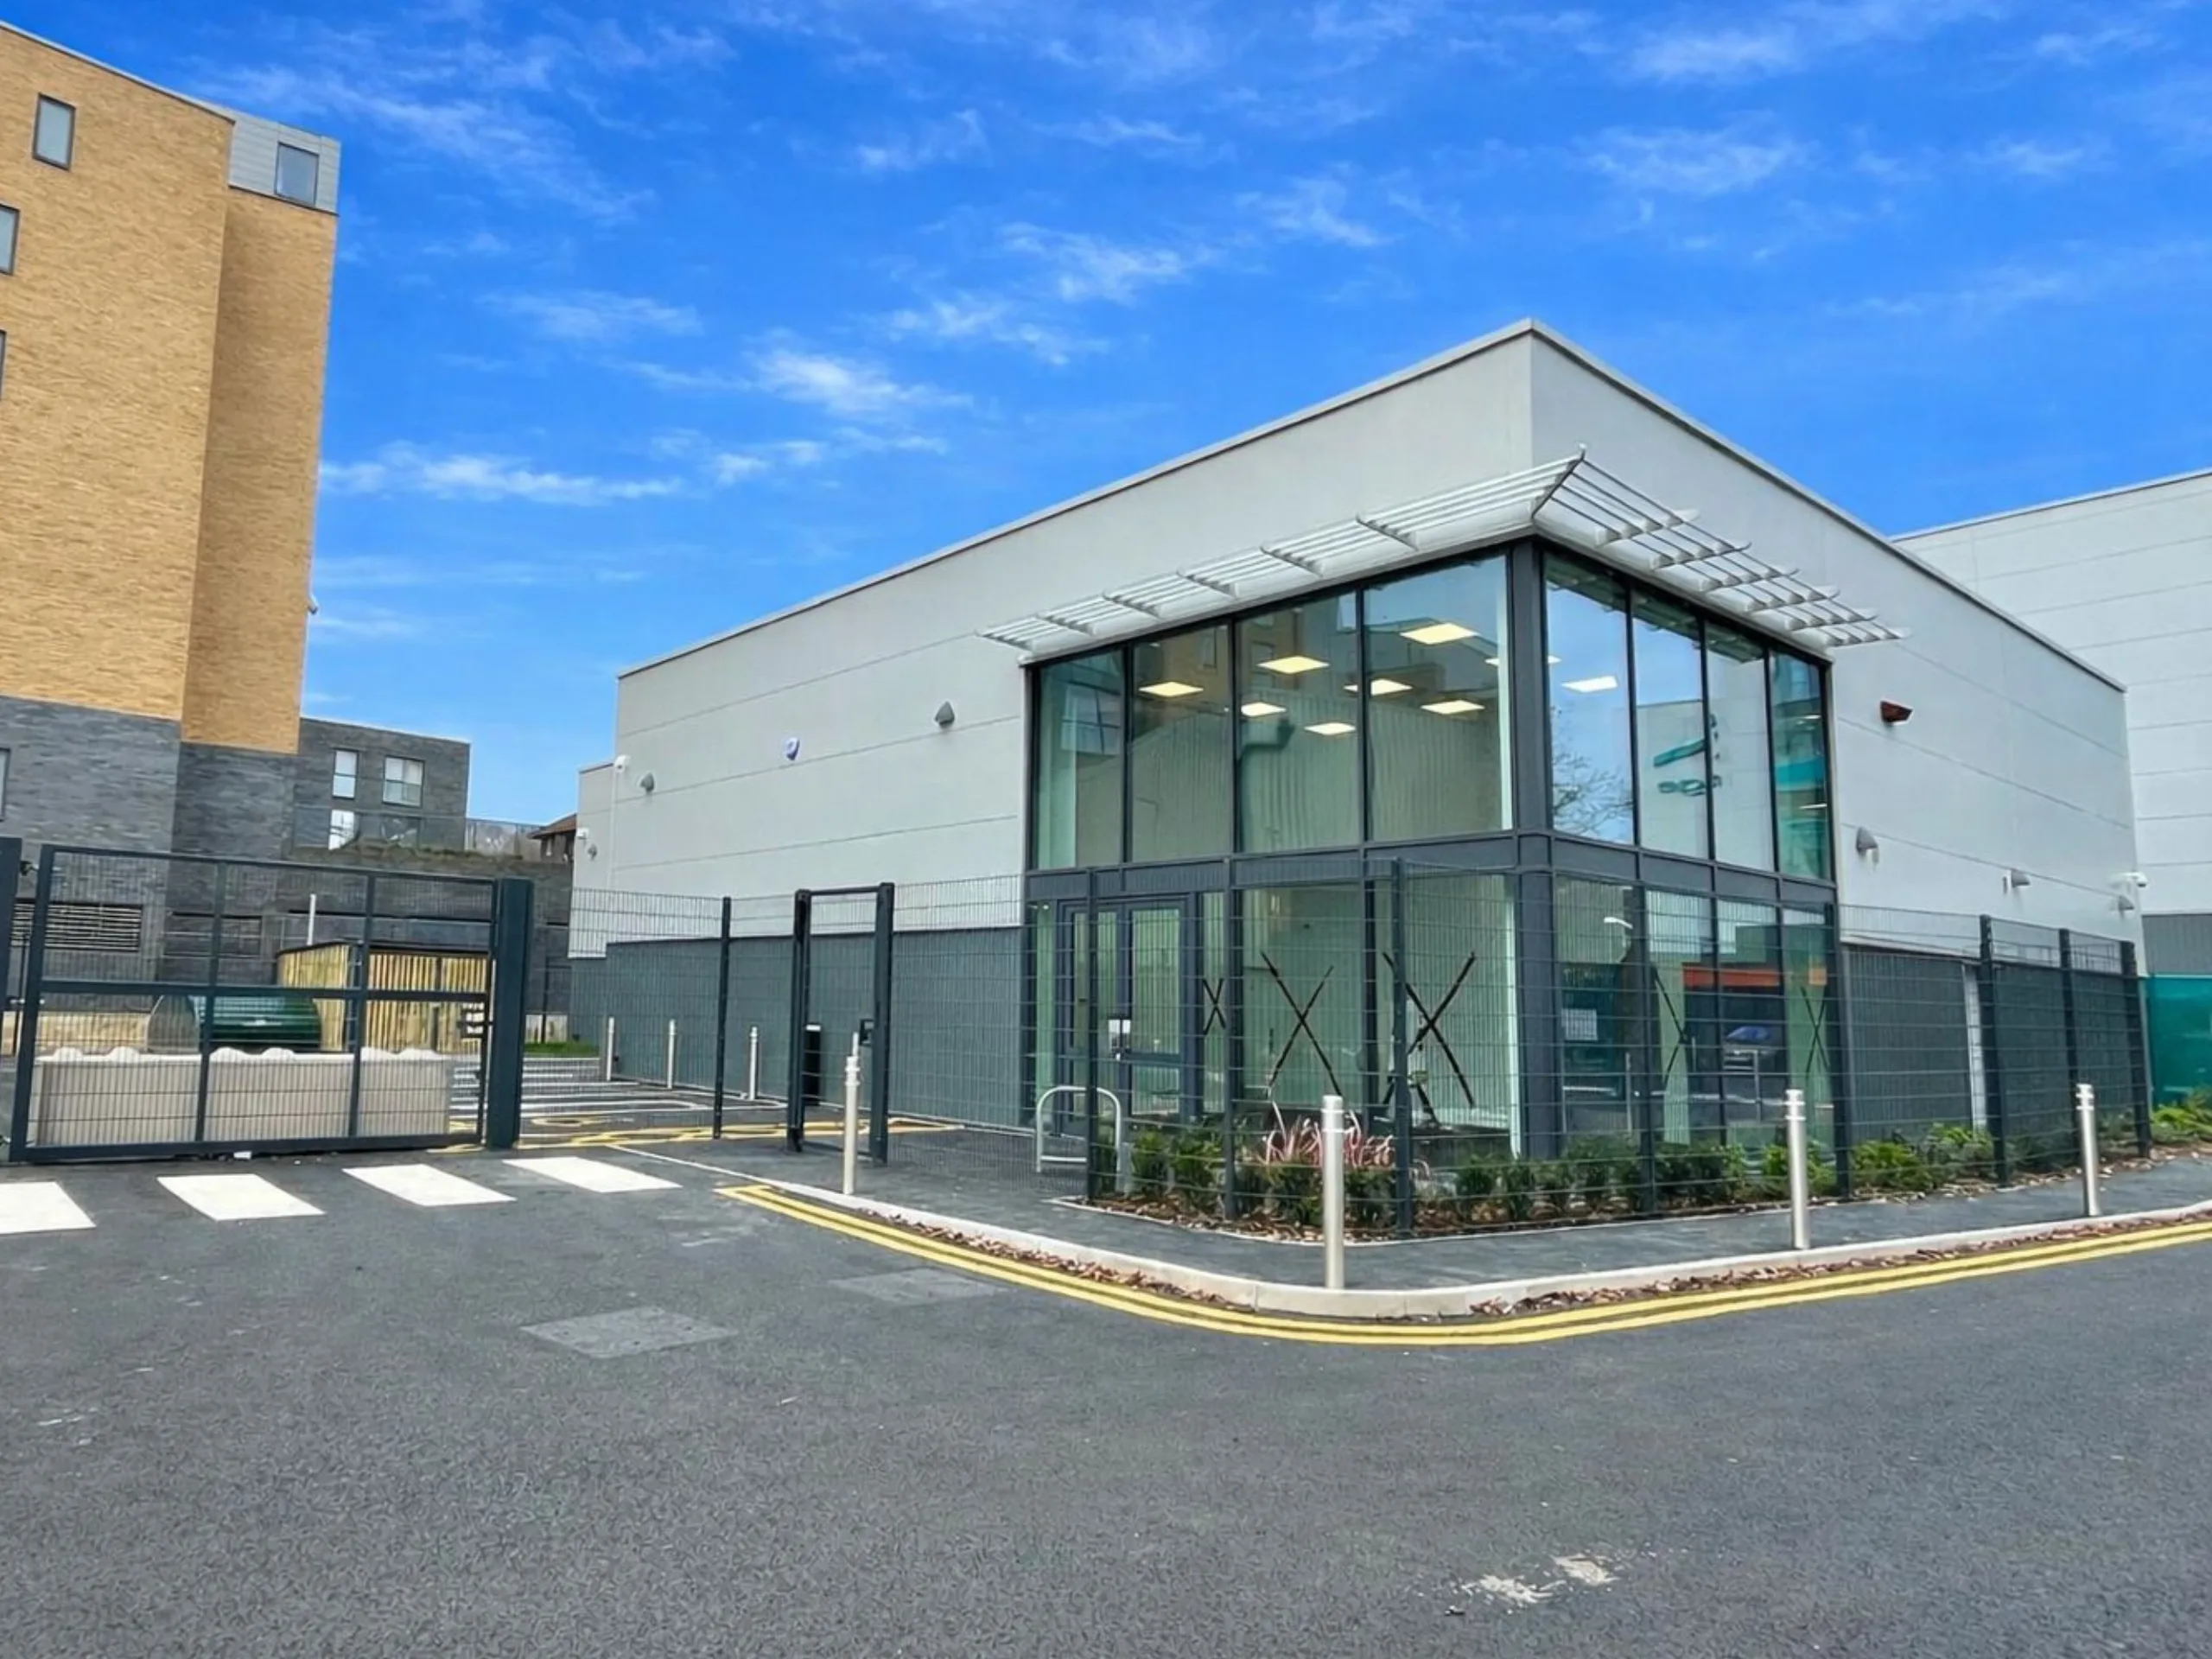

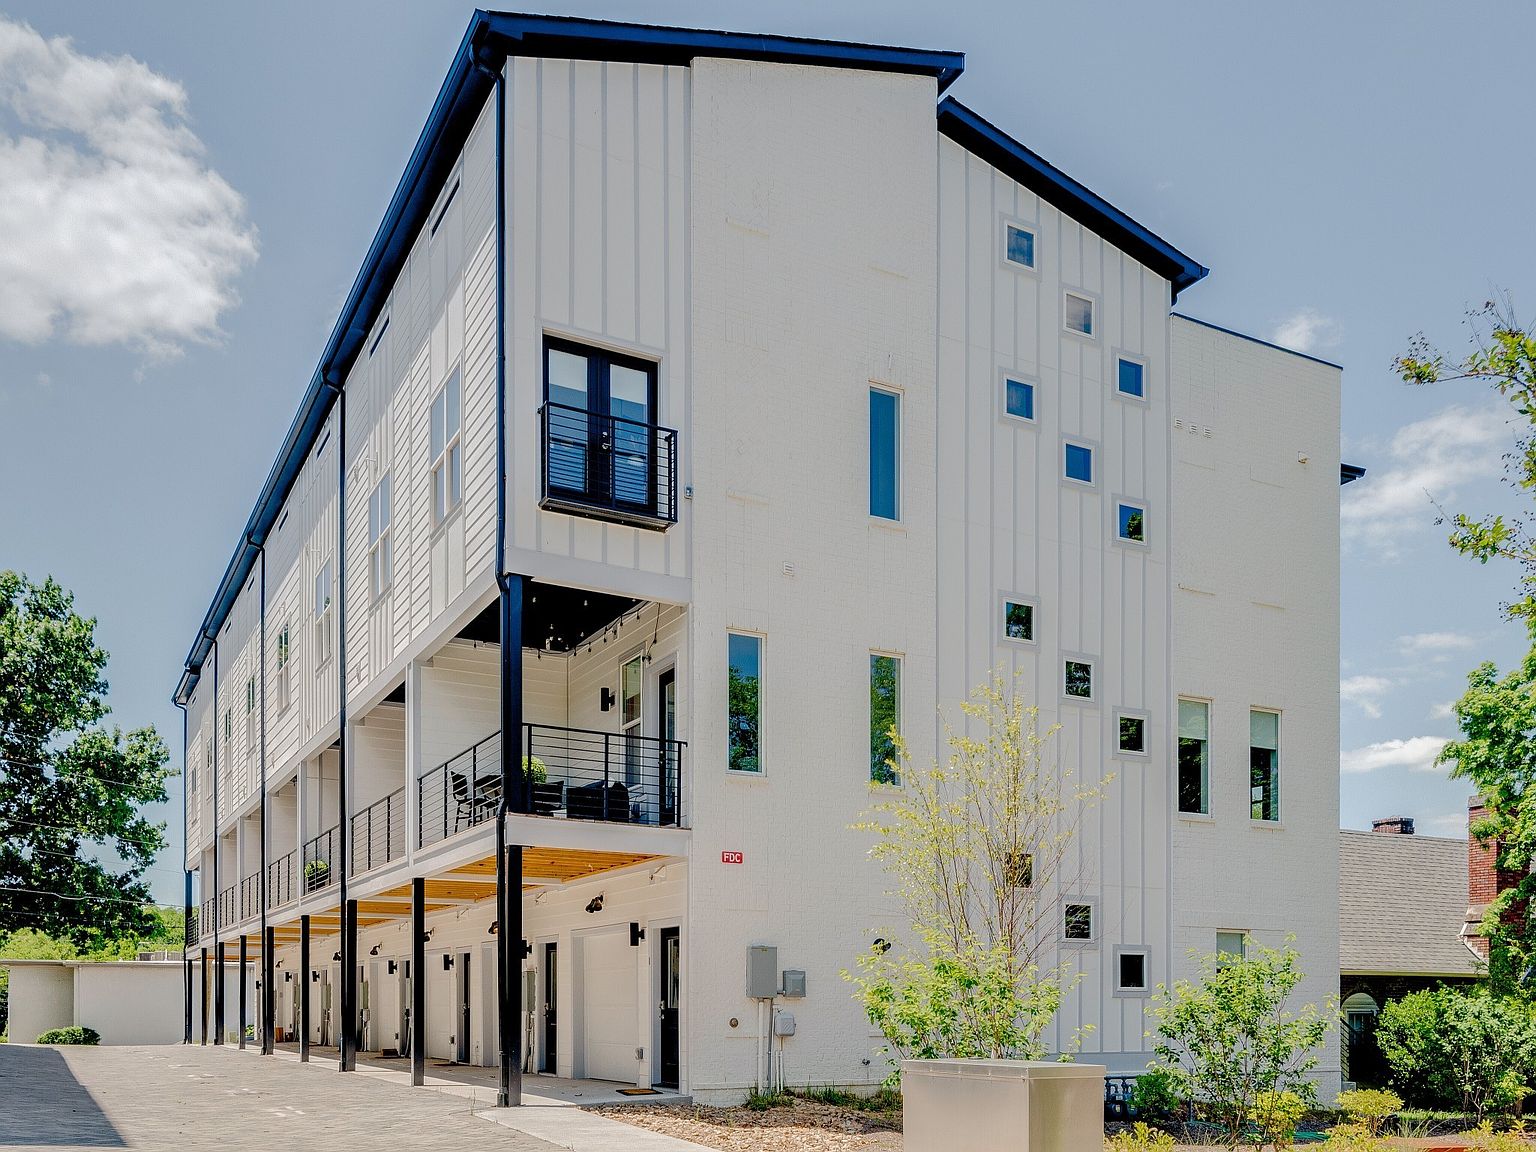
A closer look at how commercial property components may be classified for depreciation.
Commercial building structures are generally depreciated over a 39-year recovery period.
Certain qualifying equipment, fixtures, and land improvements may receive shorter recovery periods.
Illustrative asset classification only. Actual depreciation treatment depends on qualifying components and applicable tax rules.
Certain qualifying assets may have shorter recovery periods (e.g., 5, 7, or 15 years).
Earlier eligible deductions may improve cash flow depending on the owner's tax position.
The study provides structured findings for review with your tax advisor and for compliance purposes.
We gather blueprints, closing statements, appraisals, and construction costs to build a comprehensive view of your commercial asset.
Our team conducts a detailed virtual or physical site analysis to identify and quantify all structural and non-structural components.
Assets are segregated into proper MACRS recovery periods (5, 7, 15, or 39-year) based on current tax law and court precedents.
You and your CPA receive a detailed, IRS-compliant report documenting the reclassification and supporting the accelerated depreciation.
"I've had a pleasurable experience working with you guys. Clearly, this has been successful for me"
"They did a really good job keeping me informed and staying on top of things."
"I' would absolutely recommend you guys"
"These guys did a fantastic job and exceeded my expectations"
"Remote Cost Seg has a very organized process"
"Highly recommend these folks and I'll be doing more"
